Europe leads in latest pet food M&A cycle
A transatlantic divide is emerging in 2026 as European players pursue global expansion while North America prioritizes integration and margin protection.
The standard narrative often groups Western markets together, but a sharp divergence has become apparent. As US deals largely follow a defensive cycle, Europe’s regional consolidators are active locally and across the Atlantic. For management teams and investors, the signal is clear: Europeans are pursuing industrial-scale consolidation.
The transatlantic leap
The most significant development of the first half of 2026 was the emergence of European mid-caps as acquirers in the North American market. In February, Nasta Pet Food (Holding Babin), a French family-owned leader in ultra-premium nutrition, completed the acquisition of Canada’s FirstMate Pet Foods.
Supported by a €120 million ($139M) financing package, this move is not merely a geographic addition. It is a fundamental shift in industrial scale. The combined Nasta-FirstMate entity now commands a consolidated industrial capacity of 54,000 tonnes of dry pet food and 4,000 tonnes of wet pet food per year, serving over 400,000 pet families globally.
Dedicated strategy
This transaction signals that European players are no longer content with regional consolidation. They are leveraging their expertise to capture a super-premium share in the more fragmented US landscape. The transatlantic offensive is further evidenced by the United Petfood strategy.
As part of its 2026 expansion roadmap, United Petfood has a dedicated North American investment strategy, underscored by its acquisition of production facilities in Canada. The company’s ability to maintain an estimated €100 million ($115M) annual M&A spendsuggests that the ‘private label powerhouse’ model is the most resilient vehicle for global expansion in the current macroeconomic climate.
Specialization over scale
The ‘big six’ branded consolidators in Europe are shifting their focus from pure volume to category specialization. French company Nasta’s substantial Canadian acquisition was a clear example of this.
AlphaPet Ventures in Germany continues to refine the ‘digital brand platform’ model. Following its acquisition of the Belgian super-premium kibble brand CPRO FOOD in April 2026, it quickly moved to acquire Tierliebhaber, the German leader in pet supplements and functional snacks. This marks AlphaPet’s sixth acquisition since 2020, signaling a move into high- margin wellness categories that are less sensitive to raw material volatility.
After Chris Schulze-Melander joined Assisi Pet Care in the UK as CEO in August 2024, its acquisition intensity slowed. It has pivoted from lower-margin kibble to higher-margin natural treats through two acquisitions – the dog treat brands YAKERS in July 2025 and Sniffers Pet Care and its lead all-meat chew brand NAW in May 2026. The company also announced its Forthglade natural dog food deal this summer.
Premium portfolios
In a move to optimize its buy-and-build ‘machine’, VAFO Group in the Czech Republic underwent a major internal restructuring in January 2026. The group is now divided into three distinct units: VAFO Praha (flagship brands), VAFO Private Labels and VAFO Production. This structure allows VAFO to scale its manufacturing footprint in Western Europe, while maintaining the brand equity of its premium portfolios.
The Nutriment Company (formerly Voff), aNordic- backed platform based in Sweden and Germany, recently completed 12 acquisitions in a relatively short period (January 2025 to August 2026). This includes two deals that were announced in the first half of 2026, maintaining its dominance in the premium raw segment – still the fastest-growing niche in the European premium tier – while also reinforcing its presence in minimally processed foods and treats.
Inspired Pet Nutrition (IPN) in the UK has taken a pause in 2026, to allow it to integrate its French acquisitions Ultra Premium Direct and dry dog food manufacturer Sopral, which it announced in the summer of 2025. The additions provide the company with European brands and DTC expertise as well as substantial premium kibble capacity.
The protein shake-up
The alternative protein sector, once the darling of venture capital, has now entered a painful ‘reality check’ phase. The bankruptcy and judicial liquidation of Ÿnsect in the earlier part of this year served as a watershed moment for the category.
Despite raising over €600 million ($693M), the firm’s failure highlights a lack of mass customer adoption as well as the economic challenges and biosecurity issues of industrial-scale insect farming. Investor interest in this category has now shifted toward smaller, upcycled startups – like Omuu – which focus on veterinary-led functional nutrition rather than massive infrastructure.
Power of private label
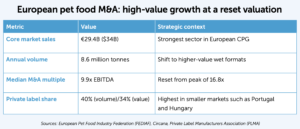
Private label has now become a lot more than just a discount-driven niche and is definitely a structural force in the European pet food sector. Data analytics firm Circana estimates its current value share at around 34% across Europe’s six largest markets.
Specialist pet retailers are increasingly building ‘good- better-best’ own-brand architectures that span natural ingredients and science or vet-led positioning. UK giant Pets at Home, for example, offers Step Up (value), AVA (veterinary-approved) and Wainwright’s (natural). Fressnapf and Maxi Zoo operate Select Gold (premium) and Real Nature (natural).
Grocers are also strengthening their premium private label ranges. However, penetration growth is showing signs of slowing – and in some markets, even declining. The two largest European groups – United Petfood and Partner in Pet Food (PPF) – have followed very different strategies over the last few years.
Buy-and-build or integration?
Backed by Waterland Private Equity, a European investment firm headquartered in the Netherlands, United Petfood is still pursuing an aggressive buy- and-build strategy. This means acquiring multiple businesses to build scale, expand geographically and strengthen its market position. An example of this is a recent investment in German wet pet food producer SmartPetPro.
Besides benefiting from its annual acquisition firepower, the company also continues to build its business through organic growth. This involves, for instance, the creation of new, greenfield capacity (wet/pouch and snacks in Poland, as well as snacks in Spain and Romania).
PPF has adopted a different course following its majority acquisition by CVC alongside existing investor Cinven in 2024. The company has stayed out of the M&A market since then, focusing on increasing integration among its pan-European network of 12 factories.
Platform mergers on their way
Looking toward 2027, the European pet M&A landscape could transition to Platform-on-Platform consolidation. Many of the private equity (PE) funds that fueled the 2020-2023 buy-and-build wave (CapVest, Axcel, Waterland, Capiton) are approaching their typical exit horizons.
The next 18 months will likely see the first major mergers between these existing platforms, as they seek the scale required for an IPO or sale to a global strategic buyer.
Future opportunities
The €1.7 billion ($2B) raised through General Mills’ recent euro bond issuance could indicate the company’s intention to pursue European M&A. Pet food would be a more resilient category than human food for future acquisitions. IPN, with its scope in European kibble and significant manufacturing capacity, would be a relevant target to add scale and bring GM’s supply chain in Europe in-house following its 2024 acquisition of Edgar & Cooper.
The strategic takeaway is that the ‘valuation premium’ of pet food has normalized. Median multiples have reset to approximately 10x EBITDA, aligning the sector with high-quality consumer packaged goods assets. For owners and managers, success in 2027 will not be measured merely by deal volume, but by the ability to integrate assets and deliver synergies across European borders.
Share this story:
One click prioritizes GlobalPETS in your search results and AI answers.